Services · Income Documentation Prep
The File That Reads as Solvent as You Are
Most self-employed applications stumble on assembly, not income. Statements arrive without the return, the return shows aggressive deductions nobody explains, and the screener — who has ninety seconds per file — sees gaps instead of a business. The documentation package is a solved problem. It just has to be assembled deliberately, in the order a screener reads it.
Free to renters — the community pays our referral fee, and your rent is identical either way.
$0
What renters pay us — the community pays the referral fee
1 day
Target from first call to your first written list
40+
Communities on our income-policy tracker
In writing
How every income policy is verified before you apply
Why this matters
What it costs to do nothing
A file that trickles in gets read in fragments, and fragments invite the slow lane: another request, another upload, another three days while the unit you toured goes to an applicant whose folder arrived complete. In a market where a well-priced San Antonio floor plan lasts a weekend, assembly speed is an advantage you already hold and most applicants leave unused.
Why clients choose us for income documentation prep
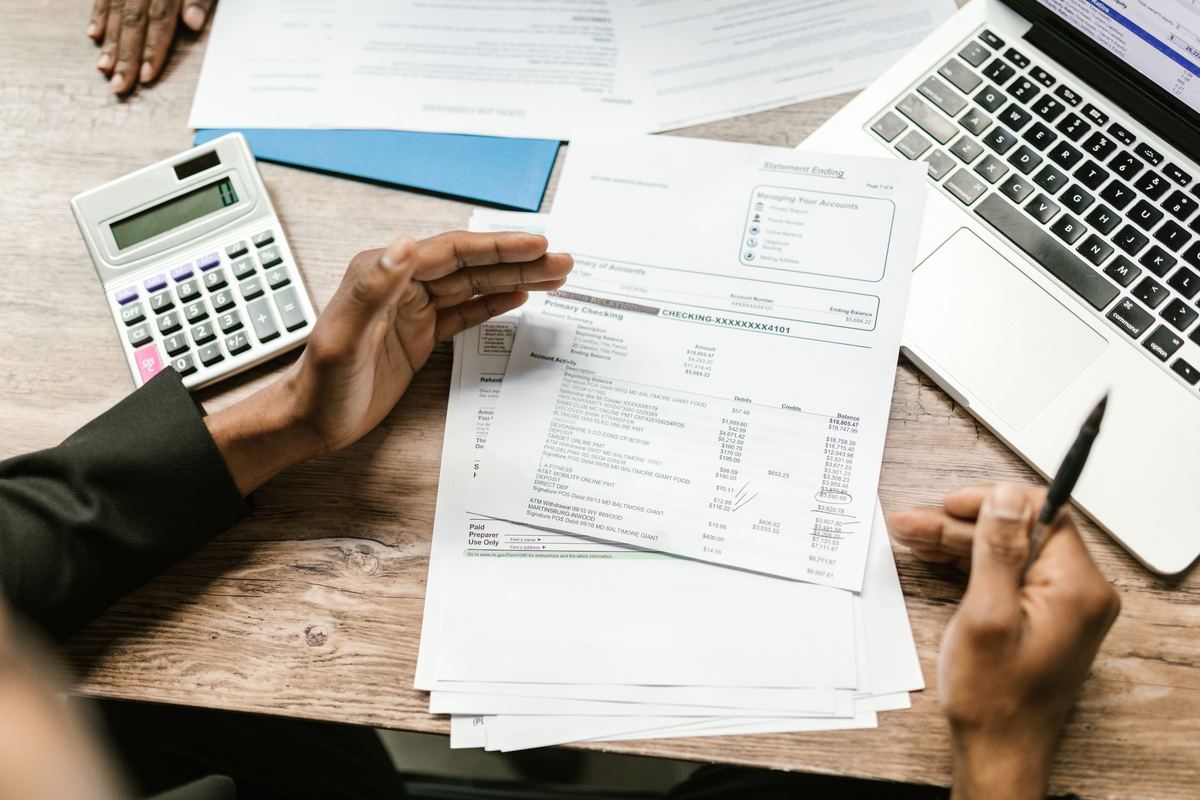
- We tell you the exact set each target community asks for — months of statements, which tax years, whether a profit and loss or a CPA letter is expected — from its current written criteria, not a forum thread.
- Order matters: a one-page summary up front, statements behind it, returns behind those. We show you the sequence screeners actually read, so the strong number is the first number they see.
- Deductions get addressed before they get questioned. If your return shows modest taxable income by design, the package explains the gap in plain words — deposits on one line, Schedule C on the next.
- The boundary stays clean: your CPA owns what your return says, and we never touch that. What we own is which documents each office accepts and how to present them.
The practical answer
Practically: once your shortlist exists, you get a per-community checklist — typically two to three months of business bank statements, one or two years of returns, and where the office weighs them, a profit and loss statement or a short CPA letter confirming self-employment. You gather; we sanity-check completeness against the written policy before anything is submitted. To be precise about the boundary: we are not accountants and give no tax advice — what your return shows is between you and your CPA. Our lane is narrower and very useful: which offices accept which documents, verified before you pay to apply.
Common questions
What is a CPA letter, and do I need one?
A short letter from your accountant confirming your self-employment, the age of the business, and typically your income as filed. Some San Antonio offices weigh it heavily, others ignore it entirely — which is why we check the target’s written policy before you ask your CPA to draft anything.
My tax return shows low income because of deductions. Is that a problem?
It can be, at offices that screen from the net figure — and it can be irrelevant at offices that screen from bank deposits. That difference is exactly what we check per community. What we never do is advise you on the return itself; that is your CPA’s work, not ours.
How many months of bank statements should I expect to provide?
Two to three months is the common written ask; some offices want more when deposits swing seasonally. We confirm the number per community so you pull statements once instead of four times.
Do you submit the application for me?
No — applications and fees run through each community’s own system, and the screening decision is theirs alone. We make sure the file you submit is complete against their written checklist, which is the part applicants most often get wrong.
Related
Other services
Self-Employed Apartment Search
Free San Antonio apartment search for 1099 and business-owner renters. We match your file to communities whose written policies accept it. $0 to you.
Learn more →
New Business Owner Search
Under two years of self-employment history? The honest San Antonio routes — larger deposits, prepaid terms, guarantors — verified per written policy. Free.
Learn more →
Commission & Seasonal Income Search
Commission checks and seasonal swings read differently under each community’s formula. We find the San Antonio offices whose math fits yours. Free.
Learn more →
Your income is real. Make the paperwork read that way.
Tell us your budget, your timing, and how the money arrives — 1099s, owner draws, commissions. We come back with communities whose written policies already have a route for it.